Shopping for senior health insurance can feel confusing. Prices change every year, and plans look different from one insurer to the next.
The good news? When you compare senior health insurance quotes the right way, you can save real money and get better coverage. This guide breaks it down in plain, simple terms.
Table of Contents
Why Comparing Senior Health Insurance Quotes Matters
Skipping this step costs money. Here’s proof.
An eHealth analysis found that people who compared their old Medicare Advantage plan against 2026 options saved an average of $1,676 per year. That’s not a small number. That’s real cash back in your pocket.
Healthcare also gets more expensive with age. Fidelity estimates that a single 65-year-old retiring in 2025 will spend about $172,500 on healthcare over their retirement. For couples, that number jumps to $345,000. And that figure doesn’t even include dental care or long-term care.
Comparing quotes helps you avoid overpaying for coverage you don’t need — and helps you spot gaps before they turn into surprise bills.
Types of Senior Health Insurance Plans to Compare
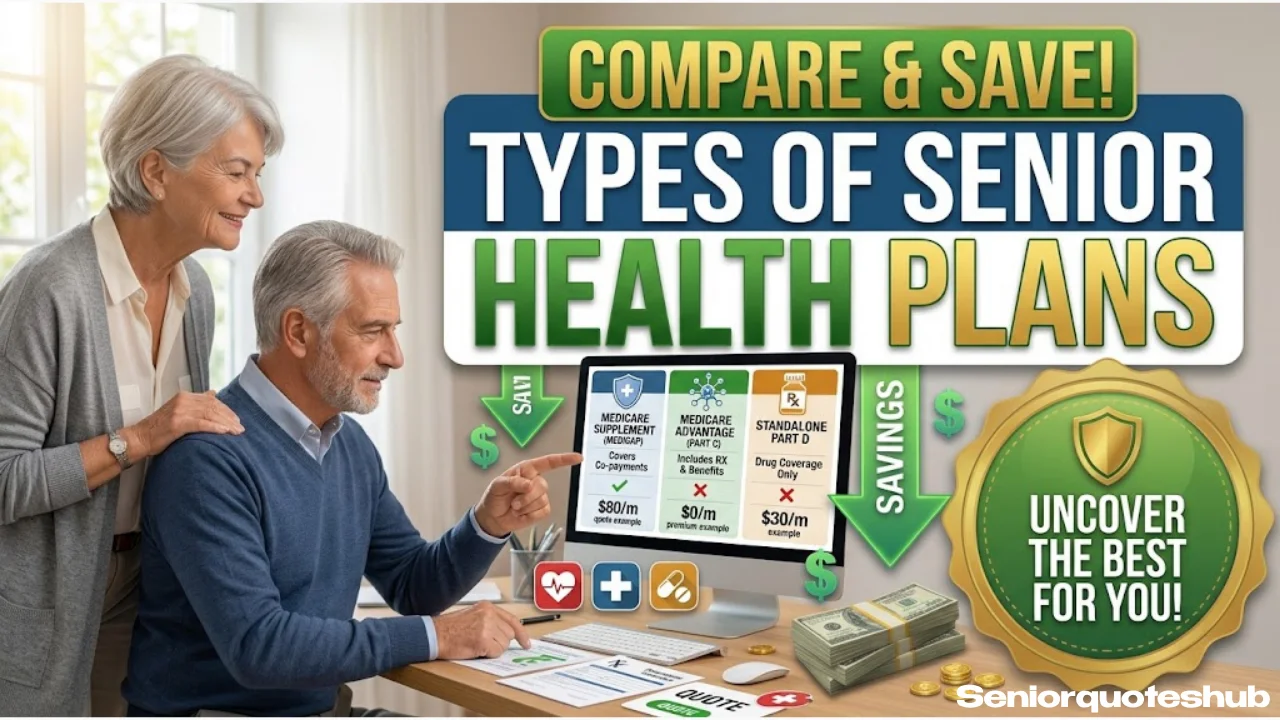
Not all senior health plans work the same way. Knowing the difference makes comparing quotes much easier.
Original Medicare covers hospital stays (Part A) and doctor visits (Part B). It’s run by the federal government and accepted almost everywhere.
Medicare Advantage, also called Part C, bundles hospital and medical coverage into one private plan. Many versions include drug coverage and extras like dental or vision.
Medigap, or Medicare Supplement Insurance, works alongside Original Medicare. It helps cover leftover costs like copays and deductibles.
Part D plans cover prescription drugs. You can pair this with Original Medicare or Medigap.
Private senior health plans matter too. Many people retire before turning 65, so they aren’t eligible for Medicare yet. These early retirees need private individual coverage until Medicare kicks in — a group often left out of typical senior insurance guides.
Must Visit : Best Senior Auto Insurance Quotes: Compare Rates & Save in 2026
How to Compare Senior Health Insurance Quotes Step by Step
Getting quotes is easy. Comparing them the smart way takes a bit more care.
Start by pulling quotes from more than one source. Use Medicare’s own plan finder, licensed insurance brokers, and direct insurer websites. Each source can surface different plan options.
Next, line up the numbers side by side. Look at the monthly premium, the annual deductible, copays, and coinsurance. A cheap premium can hide a high deductible, so check the full picture, not just one number.
Pay close attention to the out-of-pocket maximum. For 2026, Medicare Advantage plans cap in-network costs at $9,250, or up to $14,750 if the plan allows out-of-network care.
Watch for prior authorization rules too. Kaiser Family Foundation data shows about 6.4% of these requests were denied in 2022, though many got overturned on appeal. A plan with heavy prior-authorization requirements can slow down care when you need it most.
Medicare Advantage vs Medigap: Which Quote Wins?
Both options protect you, but they work in very different ways.
Medigap gives you the most freedom. You can see any doctor who accepts Medicare, and you rarely need a referral. Premiums range from about $30 to $300 a month, and out-of-pocket costs stay low. The tradeoff? You’ll usually need a separate Part D plan for drugs.
Medicare Advantage often costs less upfront. The average premium sits near $14 a month in 2026, and some plans charge nothing at all. Many bundle in dental, vision, and drug coverage. But you’ll typically need to stay in-network, and specialist visits may require a referral.
If you travel often or want maximum flexibility, Medigap tends to fit better. If you want lower monthly costs and added perks, Medicare Advantage often makes more sense. Your health needs, budget, and travel habits should guide the final call.
Mistakes to Avoid When Comparing Senior Health Insurance Quotes
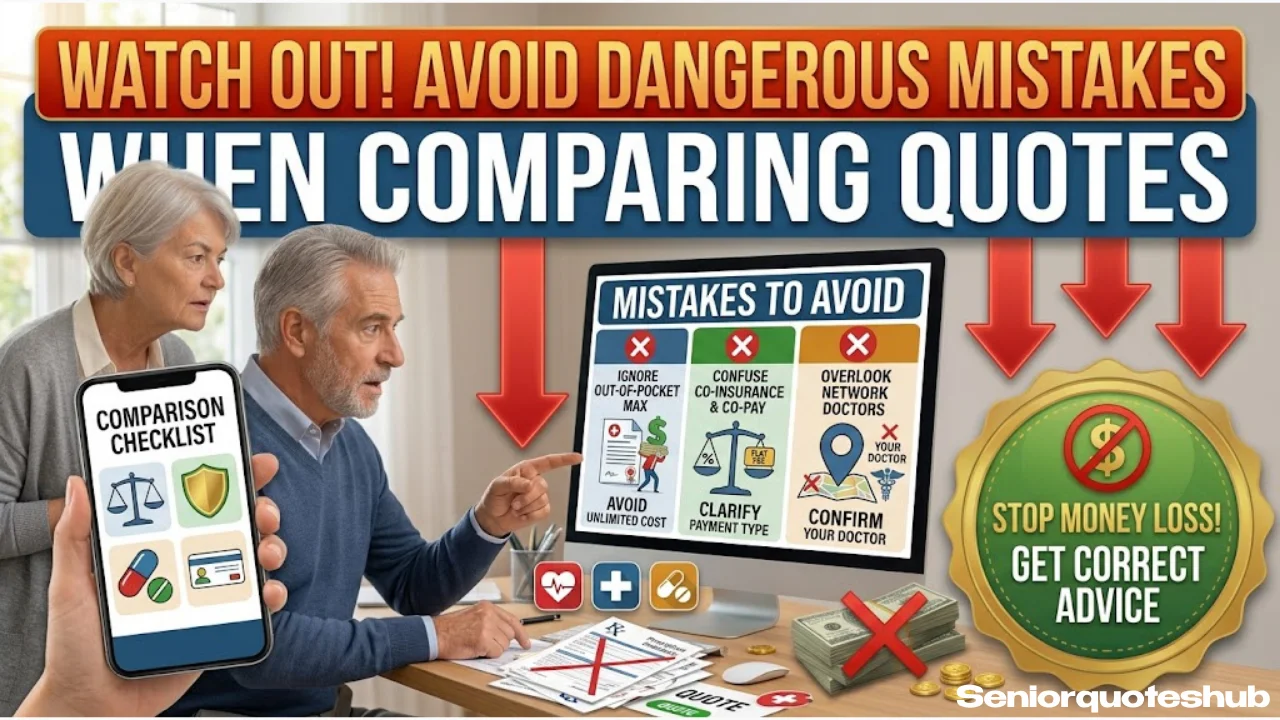
A low premium doesn’t always mean a low-cost plan. Add up the deductible, copays, and coinsurance to see the real yearly cost.
Check the plan’s star rating before signing up. This score reflects patient satisfaction and care quality, and it’s published each year by Medicare.
Don’t miss your enrollment window. Missing Medicare’s Annual Open Enrollment Period, which runs each fall, can mean waiting a full year to switch plans — or facing a late penalty.
Finally, revisit your coverage every year. Plans change their pricing, drug lists, and provider networks annually, so last year’s best deal might not be this year’s.
FAQs
What is the best way to compare senior health insurance quotes?
Gather quotes from at least three sources — a broker, an insurer, and Medicare’s official plan finder — then compare premiums, deductibles, and out-of-pocket maximums side by side.
How much does senior health insurance cost per month?
Medicare Advantage premiums average around $14 a month in 2026, while Medigap premiums typically range from $30 to $300 a month, depending on the plan and location.
Can I switch senior health insurance plans every year?
Yes. Medicare’s Annual Open Enrollment Period each fall lets you switch Medicare Advantage or Part D plans for the following year.
Is Medicare Advantage cheaper than Medigap?
Medicare Advantage usually has a lower monthly premium, but Medigap often has lower out-of-pocket costs when you need care. The cheaper option depends on how much healthcare you use.
What happens if I miss Medicare’s open enrollment period?
You may need to wait until the next enrollment period to change plans, and you could face a late enrollment penalty on some coverage types.
Conclusion
Comparing senior health insurance quotes isn’t complicated once you know what to look for. (Senior Health Insurance Quotes)Check the full cost picture, understand your plan type, and review your coverage every year. A little effort now can protect both your health and your wallet later.
Abroy Sheroz is the founder and lead content writer at Senior Quotes Hub, a website dedicated to helping students, parents, and teachers find meaningful words for graduation and senior-year milestones. With a passion for writing and a love for capturing life’s big moments in simple, heartfelt language, Abroy started this platform after struggling to find the right words for his own graduation.